The Jobs Report That Could Finally Break the Bond Market's Grip
★ ELITE MARKET POINT
Market Intelligence That Moves With You
Jobs Morning • 8:30 ET
Payrolls Likely Slowed to 90,000. Yields Hit a 24-Year High.
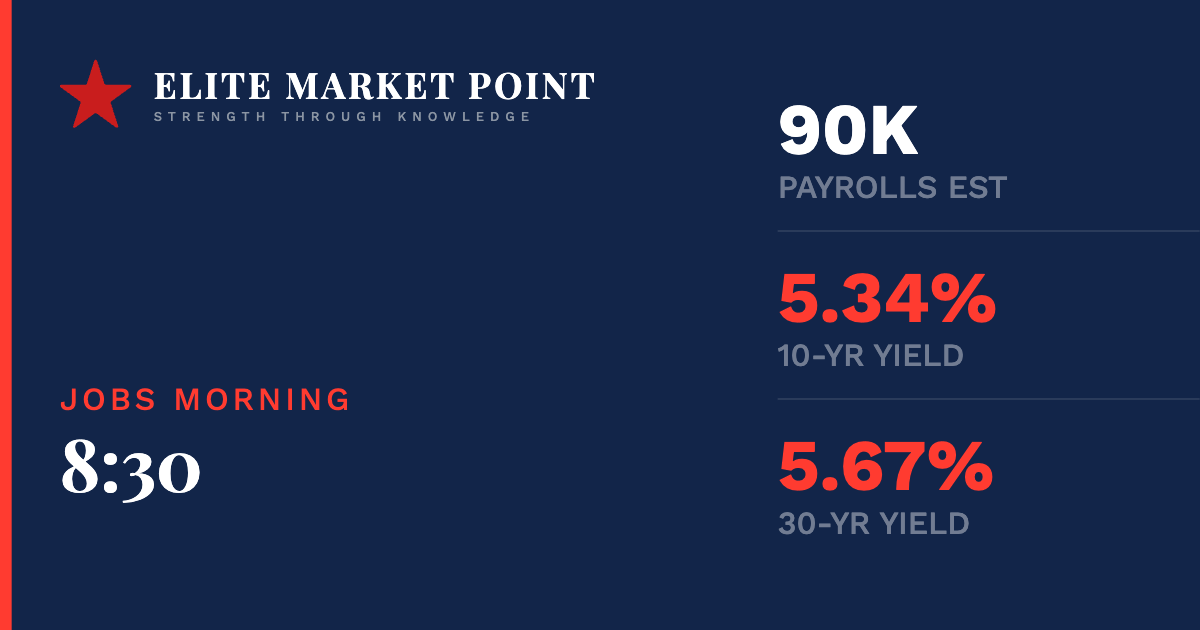
September payrolls land at 8:30. Economists expect about 90,000 jobs, down from 162,000 in August. And the 10-year just touched 5.34%, its highest in more than two decades.
We spent the week watching the bond market. This morning the labor market finally gets a word. The question is whether a weak number can do what cool inflation could not: pull yields down.
Key Idea
At 8:30 this morning, the government releases the September jobs report. Economists expect about 90,000 new jobs, down sharply from 162,000 in August, with unemployment near 4.1%. It lands while long-term yields sit at a 24-year high. Here is why it matters more than usual. Cool inflation did not move yields this week, because the selloff is about debt supply, not prices. But a weak jobs number is different. A slowing economy is the one force that reliably pulls yields down. This is the first report that can actually end the standoff.
Below is an important message from one of our highly valued sponsors. Please read it carefully as they have some special information to share with you.
Dear Reader,
Jeff Bezos is terrified.
He will be down on his knees, hands out, begging Elon for mercy.
Because Elon is about to do something that will:
Cut Amazon out of the AI race ENTIRELY…
Completely DESTROY Blue Origin…
And take control of the potential $25 TRILLION DOLLAR PER YEAR AI INDUSTRY
And in his wake, potentially create 1,806,000 NEW millionaires over the coming years…
Starting December 8th.
And this is your chance to be one of them.
Elon Musk is currently quietly planning the biggest project of his entire career.
This is bigger than Tesla, SpaceX, and X combined.
And I believe it will not only cement Elon as the winner of the AI race…
It will allow Elon to control the entire industry.
Something of this magnitude has never happened in the history of the human race.
And it’s happening FAST.
According to my timeline, you must act by December 8th.
>>>This is your free Millionaire Maker Masterclass… and it starts right now.
Sincerely,
James Altucher
P.S. I am giving away a gift worth $1,000 to the first 1,000 people who watch and take action on my Masterclass offer today. No purchase necessary. ZERO credit card required. Just click here to watch my free video, and I’ll show you how to claim yours.
What 8:30 Brings
The number to watch is payrolls. The forecast is roughly 90,000 jobs for September, a steep drop from 162,000 in August. The jobless rate is seen holding near 4.1%.
The early read already pointed this way. Private payrolls from ADP showed about 90,000 added, confirming the slowdown.
This is a hiring plateau, not a collapse. But it is the softest signal in months.
The Fed meets again this month. Today’s print helps decide whether it hikes, holds, or starts talking cuts.
Yields Won’t Quit
Thursday told the story. Stocks finished flat, with the S&P 500 near 7,680, as strength in chips like Nvidia and Micron offset the pressure from rates.
But the bond market would not let up. The 10-year yield touched 5.34%. The 30-year held near 5.67%. Both the highest in about 24 years.
Think about what they ignored. Cooler inflation on Wednesday. A Micron blowout. None of it brought yields down.
After the close, Nike posted falling revenue even as it beat on profit. One more hint the consumer is tiring.
Why This Report Is Different
Here is the distinction that matters. Inflation data is a price story, and this bond selloff is not about prices. It is about supply, the flood of new government and AI debt.
A jobs report is a demand story. It measures whether the economy itself is slowing.
That is the one thing that can cap a supply-driven selloff. If hiring is truly cooling, growth fears finally give buyers a reason to step into bonds.
So this print can move the long end in a way PCE could not. Watch how the 10-year trades right after 8:30.
The Report The Bond Market Can’t Ignore
Here’s where it gets interesting. All week, good news and bad news bounced off the bond market. Cooler prices, a chip blowout, none of it mattered, because supply sets the price of long debt right now. But demand is the override. A genuinely weak jobs number says the economy is slowing, and a slowing economy is the only thing that makes investors want safe bonds again. So this is the first print in weeks that can actually pull the 10-year down. If it comes in soft and yields still will not fall, that tells you the selloff has nothing to do with the economy at all. That would be the real warning.
Three Ways The Number Breaks
Base
Payrolls land near 90,000 and the jobless rate holds at 4.1%. In line. Yields stay near their highs and stocks chop into the weekend. Hold short-term Treasuries through SGOV to earn over 4%, keep the AI leaders through NVDA, MU and SMH, and hold energy through XOM. No need to chase before the print.
Upside
Payrolls come in soft, well under 90,000, and the 10-year finally breaks lower, under 5.2%. That is the first real relief for both stocks and bonds. The rate-sensitive names run hardest: small caps in IWM, homebuilders in XHB, and growth through QQQ. Add as the yield confirms the move down.
Risk
Payrolls run hot, above 130,000, and hike fears come roaring back. The 10-year pushes toward 5.45% and the 30-year toward 5.8%. Good news becomes bad news, and the Nasdaq gives back 2% to 4%, with high-multiple names like ARKK worst hit. Trim the richest positions and hold cash or SGOV. A hot number keeps an October hike alive.
Our View
All week we told you the bond market stopped trading the Fed and started trading supply. Today the labor market gets its say, and it is the one input that can still move the long end. Our read: a soft number is likely, near 90,000, and if yields finally ease on it, that is your first real buy signal in weeks. If yields refuse to fall even on weak jobs, respect it, because the selloff is then purely about debt, and nothing short of Washington borrowing less will stop it. So do not chase the open. Watch the 10-year right after 8:30, keep powder dry in SGOV at over 4%, and let the number pick the direction. The bond market has been right for a month. Let it lead one more time.