Why Yields Hit a 22-Year High and Stocks Still Didn't Break
★ ELITE MARKET POINT
Market Intelligence That Moves With You
Rate Reprice • Before The Bell
The 30-Year Hit a 22-Year High. Stocks Barely Blinked.
Yields ripped to levels not seen since 2004. A Trump-Xi truce extension and Hormuz-deal hopes kept stocks steady. The market is repricing to higher-for-longer. Here is Friday.
Friday, September 25. The 10-year sits at 5.19%, the 30-year at 5.48%, and the final consumer-sentiment read hits at 10 AM. The reprice is here.
Key Idea
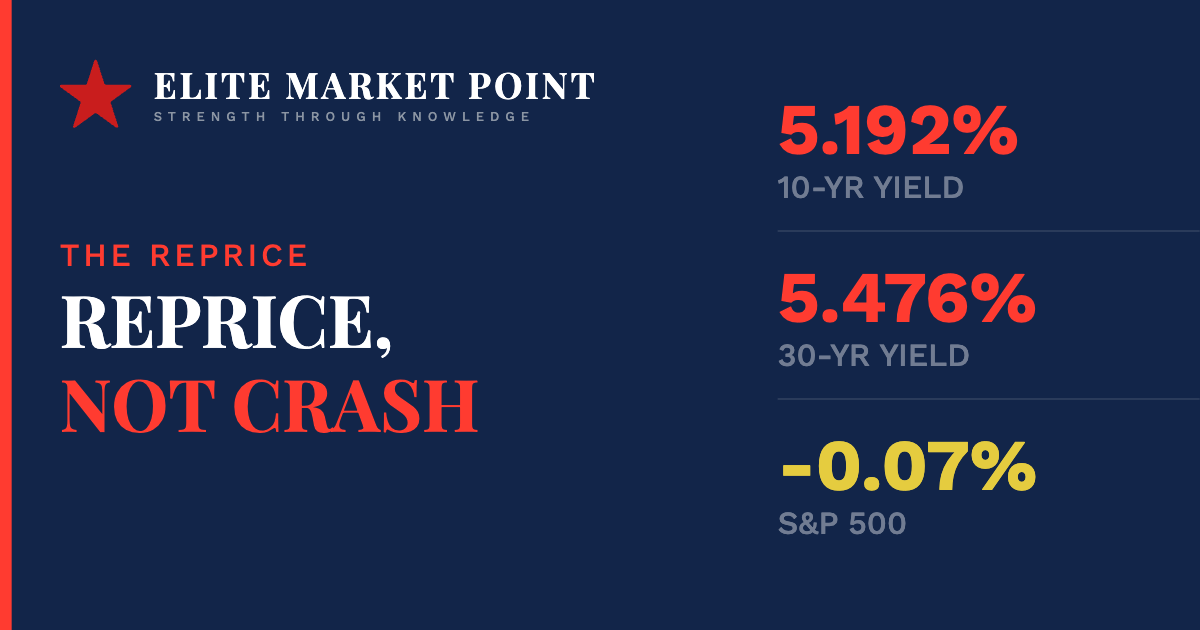
The bond market did something this week it has not done since before the financial crisis. The 10-year Treasury yield closed Thursday at 5.192%, the highest since 2007. The 30-year hit 5.476%, the highest since 2004. And yet stocks barely moved. The S&P 500 slipped 0.07%. That is not a crash. That is a reprice. Money is being marked to a higher-for-longer world in bonds, while stocks, for now, absorb it. Two things held the line: a Trump-Xi trade truce extension, and hopes of a deal to reopen the Strait of Hormuz. PCE on September 30 tests whether the calm holds.
Doroni Flight-Tested Its Prototypes. Then It Reserved $DRNI.
Doroni has already flight-tested its prototypes. Now the company has reserved the Nasdaq ticker $DRNI, marking another step toward a potential public-market debut.
At this stage, $DRNI is a ticker reservation, not a listing. Still, it comes on top of tangible progress: more than 70 test flights across the prototype program, 600+ pre-orders, and over $35M raised to date, with 15,000+ investors backing the current round.
Doroni shares are currently available at $3.30 through its Regulation A round. For a limited time, investors can receive up to 20% bonus shares.
October 22 is the last day to invest at $3.30 per share.
This is a paid advertisement for Doroni Regulation A offering. Please read the offering circular at https://invest.doroni.io/
The Week The Curve Repriced
Start with the number that ran the week. The 10-year yield.
Monday it sat near 4.95%. By Thursday it was 5.192%, a 19-year high. The 30-year, the rate that shadows your mortgage, pushed to 5.476%, the highest since 2004. A strong PMI midweek lit the fuse, and yields never looked back.
Here is what did not happen. Stocks did not break. Thursday the S&P 500 fell 0.07%, the Nasdaq 0.06%, the Russell 2000 0.17%. Flat, on a day the long bond hit a 22-year high. Oil firmed too: Brent back to $104.70, WTI to $93.12, on Strait of Hormuz tension.
We told you all week to watch the 10-year, not the headline index. This week the 10-year did all the talking, and the S&P still held near its record.
This is not a pitch deck for a café that hasn’t opened.
$1,001 buys roughly 910 shares of Green Coffee Company at $1.10 each. Behind those shares: 45 Colombian farms, about 10 million coffee trees, processing capacity over 1 million pounds a week, and products already on 3,000+ U.S. retail shelves.
Revenue went from $1M in 2021 to $26M in 2025.
The company is still private. Liquidity is limited and returns are never guaranteed.
Private investments are speculative and illiquid. Returns are not guaranteed. Review the offering circular before investing. Under Regulation A, a company may change its share price by up to 20% without requalifying the offering with the Securities and Exchange Commission.
Why Stocks Didn’t Break
A yield spike like this usually cracks equities. This time two offsets caught them.
First, Washington and Beijing extended their trade truce. Treasury Secretary Scott Bessent said the pause now runs through January 10, 2027. That removes a tariff shock the market had been pricing. Second, Reuters reported U.S. and Iranian negotiators working toward a phased deal to reopen the Strait of Hormuz. That caps the oil spike that would otherwise stack on top of the yield spike.
So what. Stocks are absorbing higher rates because the other two risks, trade and oil, just got smaller. Take either cushion away and the yield story bites. This calm is borrowed, not earned.
Watch the 30-year. When the long end stops climbing, equities exhale.
The Reprice, Not The Crash
Here is the distinction that will keep you calm and keep you careful. What happened this week was a reprice, not a crash. The bond market moved to 5% and beyond. The stock market shrugged. That is orderly. It is also conditional. Equities held only because a trade truce and an oil-deal hope arrived in the same week the yields spiked. Those are headlines, and headlines reverse. The real referee is inflation. If PCE runs hot on September 30, the 10-year pushes past 5.25%, and the calm that looked earned this week will look borrowed. Do not mistake a market that absorbed the reprice for a market that beat it. Watch the long end and the PCE print, in that order.
Three Ways Friday Goes
Base
Yields hold near 5.2% and stocks drift into the weekend. Favor what pays you to wait and what thrives on expensive money: short-term Treasuries near 5%, energy (XLE, XOM) with Brent back above $104, and cash-rich mega caps (MSFT, NVDA). The final consumer-sentiment read at 10 AM is the swing factor. The preliminary was 47.8, near a record low.
Upside
A soft sentiment print or dovish Fed talk nudges the 10-year back under 5.1%, and the beaten-down rate-sensitive names bounce: small caps (IWM), homebuilders (XHB), regional banks (KRE). The trade truce extension adds a tailwind for multinationals and chip names exposed to China. This is the relief leg, but it needs yields to actually turn.
Risk
Yields keep grinding higher into PCE and one cushion slips: a Hormuz talks breakdown or a tariff headline. Then the absorption ends and the reprice becomes a selloff. Expect 3% to 5% down in the Nasdaq and worse in small caps. Keep the cash cushion. Higher-for-longer punishes the borrower and rewards the patient.
Our View
All week we told you to watch the 10-year, not the S&P. The 10-year obeyed, ripping to a 19-year high, and the index still held. That is the story of the week: a reprice the market absorbed instead of a crash it feared. Now the new read. Do not confuse composure with safety. Stocks stayed calm because a trade truce and an oil-deal hope showed up on cue. Ride it, but keep the hedges: energy, cash-rich quality, and short-duration cash paying you to wait. The week’s last data point lands at 10 AM with consumer sentiment. The week that matters lands Wednesday with PCE. Between them, the 30-year is your tell. When it stops climbing, add risk. Until then, get paid to be patient.